Intergovernmental equalization in Russia: Assessing efficiency and the issues of reducing interregional disparities
Журнал: Economic and Social Changes: Facts, Trends, Forecast @volnc-esc-en
Рубрика: Public finance
Статья в выпуске: 4 т.19, 2026 года.
Бесплатный доступ
Growing interregional disparities and the increasing dependence of many Russian regions on federal financial assistance underscore the need to assess the efficiency of the current system of intergovernmental equalization. The aim of the study is to reveal the impact of intergovernmental transfers on regional fiscal capacity and the degree of interregional asymmetry. Drawing on Federal Treasury data on the execution of consolidated regional budgets, we conduct a comprehensive assessment of the effectiveness of the transfer mechanism for 2012–2024. By distinguishing three qualitatively different stages – pre-crisis, pandemic, and post-pandemic – we trace the evolution of the equalizing effect under changing macroeconomic conditions. The methods include statistical grouping, coefficients of variation and asymmetry, Spearman’s rank correlation, and regression analysis. The findings show that intergovernmental transfers smooth interregional disparities in budget revenues (the coefficient of variation falls by a factor of 1.5–1.7), but do not lead to a lasting reduction in the gap between the most and least fiscally secure regions (the decile ratio for total revenues remains between 2.4 and 3.0). The results also reveal a temporary weakening in 2020 of the relationship between regions’ own revenues and federal financial assistance (Spearman’s coefficient dropped to 0.58) due to the expansion of anti-crisis support during the pandemic. Moreover, the interregional hierarchy of fiscal capacity remains highly stable after transfer redistribution (Spearman’s coefficient > 0.7 in most years), pointing to the persistence of existing disparities. Overall, the current model of intergovernmental regulation is highly sensitive to external shocks while offering only a limited long-term equalizing effect: it is effective tactically in smoothing the consequences of crises but remains only partially effective strategically in ensuring long-term regional convergence. The study’s practical significance lies in the possibility of using its findings to refine intergovernmental fiscal mechanisms and design policies for narrowing regional disparities.
Короткий адрес: https://sciup.org/147255182
IDS: 147255182 | УДК: 332.14+336.15 | DOI: 10.15838/esc.2026.4.106.8
Текст научной статьи Intergovernmental equalization in Russia: Assessing efficiency and the issues of reducing interregional disparities
Pronounced interregional socio-economic differentiation remains a defining feature of Russia’s spatial development. Russia’s constituent entities differ markedly in economic activity, natural resource endowments, investment potential, and demographic profiles. These differences produce a pronounced asymmetry in regional tax bases and fiscal capacity. As A.G. Aganbegyan and E.V. Baklaeva point out, the spatial heterogeneity of the Russian economy manifests itself not only in divergent economic indicators but also in unequal access to public goods and infrastructure (Aganbegyan, 2019; Baklaeva, 2017). In this context, the system of intergovernmental fiscal relations becomes strategically important as a mechanism for preserving the financial stability of Russia’ s regions and smoothing territorial disparities.
A fundamentally important distinction in assessing the effectiveness of intergovernmental fiscal regulation is that between the “equalization” and the “smoothing” of regional differences. In Russian legislation, as in many other countries, intergovernmental transfers are intended not to fully eliminate differences among regions – objectively impossible given such pronounced spatial heterogeneity – but to reduce excessive disparities in fiscal capacity. Equalization grants to the RF constituent entities, despite their name, in fact perform the function of smoothing interregional disproportions rather than eliminating them altogether. In this study, the effectiveness of intergovernmental equalization is understood as the ability of the transfer system to ensure a sustainable reduction in regional fiscal disparities while preserving incentives for regions to develop their own revenue bases.
The issue of intergovernmental equalization is among the most debated in the modern theory of fiscal federalism. Most countries face the challenge of balancing fairness in the distribution of budgetary resources against the preservation of incentives for territories to develop their own revenue bases (Levaggi, 2002; Dougherty, Mota, 2024). The theoretical foundations of such approaches go back to the concepts of fiscal competition and the financial autonomy of subnational entities developed by Charles Tiebout (Tiebout, 1956) and further elaborated in the public finance research1
(Kollman et al., 1997; Hueglin, Fenna, 2006). Within these frameworks, a region’s ability to generate its own revenues is regarded as the most important condition for sustainable territorial development. E. Zhuravskaya’s work shows that the institutional design of intergovernmental fiscal relations influences the behavior of regional authorities, including their interest in expanding their own tax bases (Zhuravskaya, 2010).
International practice reveals a variety of approaches to intergovernmental fiscal regulation. In Germany, the fiscal equalization system is aimed primarily at reducing differences among the Lander in the level of public service provision. After the 2020 reform, the federal center’s role in resource redistribution increased, while requirements for spending efficiency and regional fiscal responsibility were maintained2 (Leonardy, 1999).
The American model is characterized by greater state autonomy in the tax sphere. Equalization is achieved mainly through targeted federal support programs, which fosters regional competition but simultaneously widens differences in the fiscal capacity of territories. The pandemic experience exposed the vulnerability of less well-off states, which required additional federal budget assistance (Gamkhar, 2002; Frieden, 2024; Dougherty et al., 2024).
The Canadian system combines a high degree of provincial autonomy with a well-developed mechanism of equalization transfers based on assessments of tax capacity. At the same time, this approach is criticized for potentially weakening incentives for territories to develop their own revenue bases (Beland et al., 2017).
India’s experience demonstrates the need to take into account not only financial but also demographic and infrastructural differences among regions. Transfers are distributed through the Finance Commission, using both equalization instruments and support mechanisms for regions aimed at improving governance performance (Chakraborty, 2026; Malik et al., 2025).
A comparison of the experience of various federal states shows that the effectiveness of intergovernmental fiscal regulation is determined not only by the volume of redistributed resources but also by the extent to which the system creates incentives for territorial development. The practices of Germany, the United States, Canada, and India illustrate different ways of combining these objectives: equalization mechanisms help reduce differences in regional fiscal capacity, but their longterm effect depends on accounting for the factors that expand territories’ own revenue bases. At the same time, international experience shows that in times of crisis most federal states strengthen the center’s role in redistributing financial resources, after which regulatory mechanisms are adapted to the new conditions. An important element of modern systems is also the consideration of regional authorities’ performance when providing certain types of support, which makes it possible to combine the compensatory and incentive functions of transfers. For Russian practice, it is particularly important to strike a balance between the objectives of budgetary equalization and the creation of conditions for regional economic development. The experience of foreign countries shows that the sustainability of an intergovernmental fiscal system requires regular adjustment of its parameters in response to structural changes in the economy and differences in territorial potential.
In the Russian scholarly literature, the issues of intergovernmental fiscal relations are examined mainly through the lens of the financial autonomy of the federation’s constituent entities, the consequences of fiscal centralization, and the effective- ness of intergovernmental transfer mechanisms (Akindinova et al., 2018; Balaev, 2018; Pechenskaya-Polishchuk, 2023). A.G. Bukhvald emphasizes that the current model of Russian fiscal federalism is characterized by a high degree of centralization of financial resources and by the growing dependence of a significant number of regions on federal assistance (Bukhvald, 2022). Similar conclusions are presented in the study by N.V. Golovanova and E.A. Dombrovsky (Golovanova, Dombrovsky, 2016). A number of researchers highlight the ambiguous impact of intergovernmental transfers on economic growth and on the structure of regional economies (Mikhaylova et al., 2018; Chernyshova, 2016).
A separate line of research concerns fiscal disparities among Russian regions. M.Yu. Malkina examines the convergence and divergence of the RF constituent entities in terms of fiscal capacity using a decomposition of the Theil – Bernoulli indices and concludes that stable interregional heterogeneity persists (Malkina, 2016). Many researchers stress that fiscal disparities among Russian regions remain considerable even amid active intergovernmental redistribution (Bogacheva, Smorodinov, 2019; Zubarevich, Safronov, 2023). A.M. Kalinin pays particular attention to the structure of regional budget revenues and to the problem of incentives for expanding own revenue bases (Kalinin, 2021).
In recent years, the analysis of crisis shocks and their impact on the transformation of intergovernmental fiscal policy has become increasingly prominent. The COVID-19 pandemic required a large-scale expansion of federal support to the constituent entities of the Federation and brought about substantial changes in the parameters of intergovernmental fiscal regulation. As I.V. Karavaeva and co-authors note, the strengthened role of the federal budget during the crisis became one of the key factors in maintaining the country’s economic stability (Karavaeva et al., 2021). At the same time, the increase in federal support did not in itself ensure a sustainable reduction in regional disparities (Bashenkov et al., 2022). Research on the post-pandemic period shows that transfers perform a dual function: they help reduce fiscal risks and maintain regional stability, but they simultaneously increase the dependence of individual territories on federal decisions (Bukina, 2022; Timushev, Mikhaylova, 2023; Mokhnatkina, 2023). In this regard, the debate continues as to how well the current model of intergovernmental fiscal regulation contributes not only to equalizing fiscal capacity but also to developing the own revenue bases of the RF constituent entities.
Of considerable interest are studies devoted to improving the federal policy for equalizing regional budget revenues. V.N. Timushev analyzes the main directions for improving the mechanisms of fiscal capacity equalization in the RF constituent entities, arguing for the need to enhance the effectiveness of intergovernmental fiscal regulation while taking into account the specific features of regional socio-economic development. The author emphasizes the problem of preserving incentives for regions to expand their own revenue bases under the redistribution of financial resources through the system of intergovernmental transfers (Timushev, 2025). The role of equalization grants in changing regional budget inequality is analyzed by D.Yu. Zemlyansky and co-authors, who note the stability of the composition of the regions receiving the largest volumes of grants (Zemlyansky et al., 2024). Current approaches to intergovernmental fiscal regulation and the provision of financial support to the RF constituent entities in the planning period are examined in the work of S.I. Shabelnikova, making it possible to assess modern trends in transfer policy (Shabelnikova, 2024; Shabelnikova, 2025). The assessment of interregional disproportions in the context of the policy of equalizing spatial development is presented by I.A. Antipin and co-authors, who confirm the persistence of significant differences among the RF constituent entities (Antipin et al., 2025).
Despite the large number of studies on intergovernmental fiscal relations, a number of issues remain debatable. In particular, the long-term effectiveness of the Russian equalization system and its impact on the persistence of regional disparities remain underexplored. Most works focus on individual instruments of transfer policy or on particular periods, which limits the ability to assess its long-term consequences. Moreover, additional analysis is needed not only of changes in regional fiscal capacity but also of the persistence of differences in their financial positions after resource redistribution. The question of how well the current system of intergovernmental fiscal regulation ensures the long-term convergence of the RF constituent entities, rather than merely temporary smoothing of the consequences of external shocks, remains insufficiently studied.
Accordingly, the aim of this work is to assess the effectiveness of intergovernmental transfers as an instrument for reducing interregional disparities in the fiscal capacity of the RF constituent entities in 2012–2024. To achieve this aim, the following objectives are addressed:
-
1) the dynamics and structure of budget revenues of Russian regions over the period under study are analyzed, distinguishing three stages: precrisis (2012–2019), pandemic (2020–2021), and post-pandemic (2022–2024);
-
2) the degree of interregional differentiation of tax and non-tax revenues, as well as total revenues including transfers, is quantitatively assessed using coefficients of variation, skewness, and the decile ratio;
-
3) the stability of the interregional hierarchy of fiscal capacity is assessed using Spearman’s rank correlation coefficient;
-
4) the orientation of federal transfer policy is identified through regression analysis;
-
5) recommendations are formulated for improving the mechanisms of intergovernmental fiscal regulation.
The scientific novelty of the study lies in identifying the specific features of changes in the equalizing role of intergovernmental transfers in Russia during 2012–2024, a period that includes pre-crisis, pandemic, and post-pandemic stages. Unlike approaches focused mainly on assessing the scale of resource redistribution, this work examines how transfers affect the persistence of the interregional hierarchy of fiscal capacity. Drawing on an analysis of regional revenue dynamics and the use of variation measures, the decile ratio, and Spearman’s rank correlation, it is shown that federal financial support reduces differences among territories but does not lead to a substantial change in the relative positions of regions within the system of fiscal capacity. This provides a basis for arguing that equalization mechanisms should be combined with instruments aimed at developing the own revenue bases of the RF constituent entities.
Description of the research methodology and its rationale
The information base of the study includes data from the official website of the Federal Treasury of the Russian Federation on the execution of the consolidated budgets of the RF constituent entities for 2012–2024. Three types of budget revenues per capita are analyzed: tax and non-tax revenues, nonrepayable receipts from the federal budget, and total regional budget revenues. To ensure comparability, all monetary indicators are converted to constant 2012 prices and adjusted by the budget expenditure index. The research methodology comprises four consecutive stages.
At the first stage, the dynamics and structure of regional budget revenues are analyzed using statistical grouping into interval categories of per capita revenues (with a step of 20,000 rubles). This makes it possible to identify structural shifts in the distribution of regions under the influence of macroeconomic shocks and the transformation of intergovernmental fiscal policy.
At the second stage, interregional heterogeneity is quantified. Means, asymmetry ranges, coefficients of variation, and decile ratios are calculated. The analysis is conducted for both tax and non-tax revenues and total revenues, which makes it possible to assess the smoothing effect of transfers.
At the third stage, the stability of the interregional hierarchy of fiscal capacity is assessed using Spearman’s rank correlation coefficient:
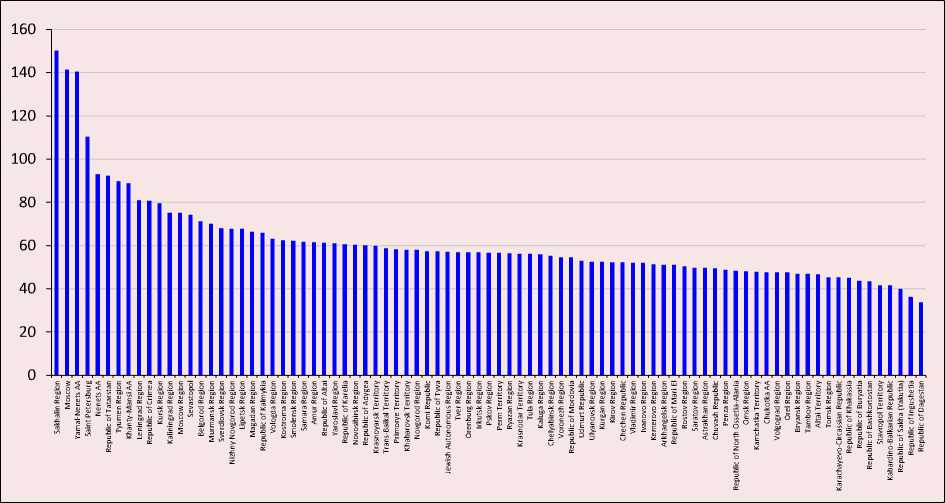
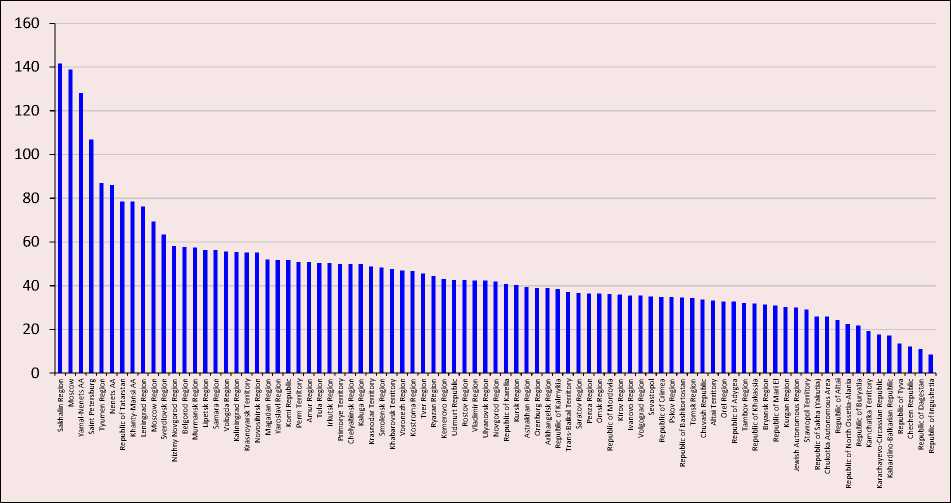
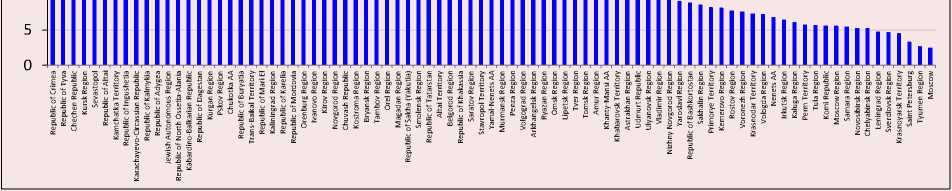
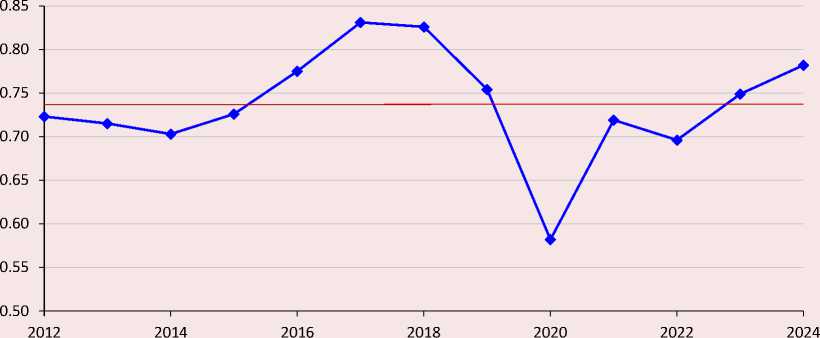
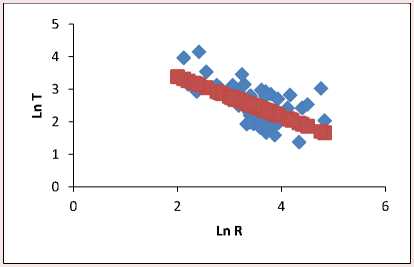
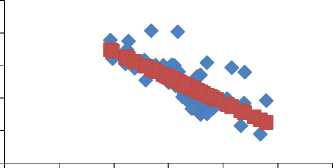
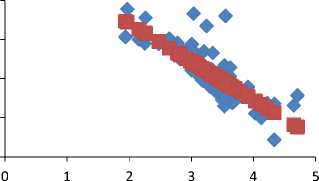
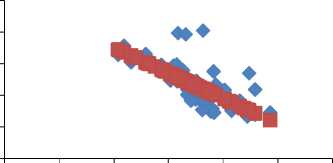
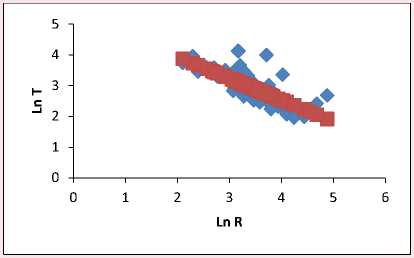
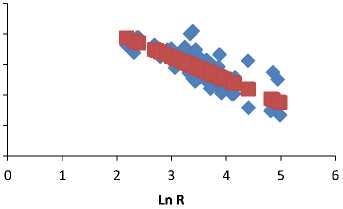
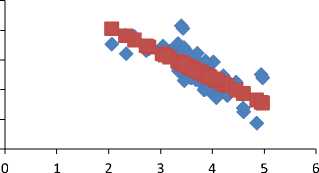
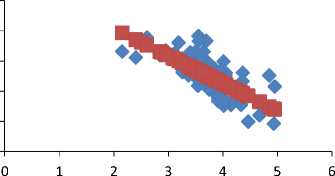
= i - 6 • ^ The choice of a non-parametric method is due to the skewed distribution of regional revenues and the need to assess changes not in absolute values but in the relative positions of regions. Coefficient values close to 1 indicate the preservation of the hierarchy after the distribution of transfers. At the fourth stage, the orientation of federal transfer policy is assessed using a regression model of the relationship between the logarithm of per capita non-repayable receipts (lnT) and the logarithm of per capita tax and non-tax revenues (lnR): In Ti = a + P ■ In Ri + £t. The use of logarithms makes it possible to interpret the coefficient β as an elasticity indicator, i.e., as a measure of the response of intergovernmental transfer volumes to changes in the own revenues of the RF constituent entities. If the coefficient takes a negative value, this indicates an equalizing orientation of fiscal policy: more assistance is directed to regions with lower tax and non-tax revenues. A positive value of β, by contrast, indicates that resources are concentrated in better-off regions. The model was estimated separately for each year using the least squares method, which made it possible to track changes in intergovernmental fiscal relations over time. Thus, the sequential application of grouping methods, variation measures, rank correlation, and regression analysis makes it possible to examine various aspects of the functioning of the fiscal equalization system: changes in the revenue structure, the degree of interregional heterogeneity, the stability of the fiscal hierarchy, and the orientation of redistributive processes. When interpreting the results, the study’s limitations should be taken into account. The methods used allow statistical relationships to be identified but do not establish causal links. In addition, the analysis is conducted without disaggregating transfers by type, although grants, subsidies, and subventions have different purposes. Grants are aimed at equalizing current fiscal capacity, subsidies at co-financing expenditures, and subventions at financing delegated powers. Each of these instruments affects the financial positions of regions differently, and their aggregated analysis may obscure the specific nature of their impact. In particular, subventions, which are strictly tied to delegated powers, depend less on a region’s level of own revenues, which may distort the overall picture of the equalizing effect. Research results and discussion Dynamics of budget revenues of Russian regions: Analysis of trends The distribution of regional budgets by the level of total per capita budget revenues is presented in Table 1. A graphical interpretation of the distribution of the RF constituent entities by total per capita budget revenues as of 2024 is shown in Figure 1 (for clarity, the regions are arranged in descending order of revenues). The analysis revealed a number of stable trends in the dynamics of fiscal capacity of the RF constituent entities. In the pre-crisis period (2012– 2019), there was a gradual decline in the number of regions in the group with per capita total revenues of 50–70 thousand rubles: from 12 in 2012 to 8 Table 1. Grouping of the RF constituent entities by the volume of total budget revenues per capita, number of regions
Revenue, thousand rubles
Period under consideration
Pre-crisis
Pandemic
Post-pandemic
2012
2013
2014
2015
2016
2017
2018
2019
2020
2021
2022
2023
2024
from 10 to 30
1
0
2
6
6
4
0
0
0
0
0
0
0
from 30 to 50
61
63
64
67
65
66
67
60
39
24
27
24
23
from 50 to 70
12
14
10
5
8
8
8
15
36
47
45
47
46
from 70 to 90
5
2
5
5
4
5
5
4
5
8
8
7
10
from 90 to 110
2
3
2
1
1
1
4
3
3
3
1
4
2
from 110 to 130
0
1
2
0
1
1
0
1
1
2
1
0
1
above 130
2
0
0
1
0
0
1
2
1
1
3
3
3
Calculated from: materials from the official website of the Federal Treasury of the Russian Federation. Available at:
Figure 1. Distribution of regions by total budget revenues in 2024 Calculated from: materials from the official website of the Federal Treasury of the Russian Federation. Available at: in 2016–2018, followed by an increase to 15 in 2019. The group with revenues of 30–50 thousand rubles contained the absolute majority of the RF constituent entities during this period (from 60 to 67). Thus, the pre-crisis period was characterized by the concentration of the bulk of regions in the lowest income group. In the pandemic period (2020–2021), the most noticeable structural shifts occurred. The number of regions in the group with revenues of 50–70 thousand rubles increased sharply, from 15 in 2019 to 36 in 2020 and 47 in 2021. At the same time, the number of regions with per capita revenues of 30– 50 thousand rubles decreased significantly, from 60 in 2019 to 39 in 2020 and 24 in 2021. These changes coincide with a sharp increase in federal financial assistance in the respective years (see Tab. 5), which makes it possible to link the structural shifts to the expansion of anti-crisis support for the regions. In the post-pandemic period (2022–2024), the established structure was generally preserved: the number of regions in the group with per capita revenues of 50–70 thousand rubles stabilized at 45– 47, while the group with 30–50 thousand rubles remained at 23–27 regions. By 2024, the number of regions in the 50–70 thousand rubles group had reached 46, more than three times the 2019 level (15 regions). This indicates a shift of the bulk of the RF constituent entities into groups with higher fiscal capacity, but this shift occurred mainly during the pandemic period and did not intensify further. The minimum values of per capita revenues of consolidated budgets during most of the study period were typical primarily of constituent entities with a limited own revenue base, high dependence on federal financial assistance, and a relatively low level of economic activity. This group included several republics of the North Caucasian Federal District, some agriculture-oriented regions, and territories with limited industrial and investment potential. At the same time, the number of regions with the highest level of total revenues (above 70 thousand rubles per capita) remained comparatively limited throughout the period under review, despite a gradual increase in their number by the end of the study period. This group consisted mainly of financially stable constituent entities with a high concentration of the resource sector, a developed industrial base, and significant tax potential. Unlike total revenues, which include intergovernmental transfers, tax and non-tax revenues reflect the ability of regions to generate financial resources independently. This indicator is therefore more closely related to the specific features of a territory’s economy, its sectoral structure, and the scale of its tax base. The distribution of regions by the level of own revenues gradually shifted toward higher values (Tab. 2). Whereas in 2012–2017 most RF constituent entities were in the 10–30 thousand rubles per capita range, in subsequent years the main range moved to the 30–50 thousand rubles group. In 2022–2024, this trend continued: the number of regions with per capita revenues of 30–50 thousand rubles rose from 38 to 43, while the number in the 50–70 thousand rubles range increased from 11 to 20. Table 2. Grouping of the RF constituent entities by the volume of tax and non-tax budget revenues per capita, number of regions Revenue, thousand rubles Period under consideration Pre-crisis Pandemic Post-pandemic 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 below 10 3 3 5 5 5 5 3 3 3 2 1 1 1 from 10 to 30 37 36 42 50 46 41 35 36 37 30 29 15 12 from 30 to 50 33 35 29 21 26 29 37 36 35 35 38 45 43 from 50 to 70 5 4 3 3 4 5 3 3 6 12 11 16 20 from 70 to 90 3 4 3 4 2 4 4 3 1 1 2 3 5 from 90 to 110 0 0 2 1 1 0 2 2 2 3 0 2 1 from 110 to 130 2 1 1 0 1 1 1 1 0 1 2 1 1 above 130 0 0 1 0 0 0 1 1 1 2 2 2 Calculated from: materials from the official website of the Federal Treasury of the Russian Federation. Available at: Despite the overall growth of the indicator, differences among the RF constituent entities remained considerable. A high level of own revenues was maintained mainly in regions with developed industrial production, a strong extractive sector, and a high concentration of economic activity. At the same time, the composition of regions with the lowest indicator values changed only slightly, which points to the persistence of differences in the tax potential of territories. The continued heterogeneity of own revenues determines the need to use intergovernmental transfers as an instrument for compensating differences in the financial capacity of regions (Fig. 2). Changes in the volume of non-repayable receipts (Tab. 3) reflect the impact of crisis periods on the scale of resource redistribution. Before 2019, transfers of less than 10,000 rubles per capita were typical of most RF constituent entities. In 2020, the situation changed markedly: the number of regions Figure 2. Distribution of regions by tax and non-tax budget revenues in 2024 Calculated from: materials from the official website of the Federal Treasury of the Russian Federation. Available at: (accessed: April 2026). Table 3. Grouping of the RF constituent entities by the volume of non-repayable receipts per capita, number of regions Revenue, thousand rubles Period under consideration Pre-crisis Pandemic Post-pandemic 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 below 10 30 41 46 52 55 51 42 30 7 11 11 19 27 from 10 to 30 49 37 34 29 26 29 38 47 63 64 62 58 52 from 30 to 50 2 5 3 4 4 4 2 6 11 8 10 6 6 from 50 to 70 2 0 2 0 0 1 3 2 4 2 2 2 0 Calculated from: materials from the official website of the Federal Treasury of the Russian Federation. Available at: receiving less than 10,000 rubles fell from 30 to 7, while the number of regions with transfers above 30,000 rubles increased from 8 to 15. In subsequent years, support volumes gradually declined, and by 2024 the number of regions receiving less than 10,000 rubles per capita reached 27. The largest volumes of federal assistance went to regions with limited capacity to generate own revenues, a high social burden, and substantial expenditure obligations. This group consisted mainly of several republics of the North Caucasus, national republics, and territories with difficult natural and climatic conditions. At the same time, the composition of the main recipient regions remained largely unchanged throughout the period. The smallest volumes of support were typical of regions with a more developed economic base and high tax potential (Fig. 3). The results show that the system of intergovernmental redistribution is oriented to a considerable extent toward supporting regions with limited tax potential and a high need for fiscal equalization. At the same time, the persistent large differences in federal financial assistance and the stability of the group of regions receiving the largest transfers indicate a high degree of heterogeneity in the socio-economic development of the RF constituent entities and the entrenchment of existing disproportions. When analyzing intergovernmental fiscal regulation, it must be borne in mind that the equalization of the fiscal capacity of the RF constituent entities is achieved not only through direct intergovernmental transfers but also through the redistribution of certain federal tax revenues. Thus, part of the receipts from excise taxes on Figure 3. Distribution of regions by non-repayable receipts in 2024 Calculated from: materials from the official website of the Federal Treasury of the Russian Federation. Available at: alcoholic beverages and petroleum products is distributed among regions according to established norms and in practice performs the functions of intergovernmental transfers. An additional influence on interregional redistribution came from changes in the proportions of corporate profit tax distribution starting in 2017, accompanied by a one-percentage-point reduction in the regional component of the tax rate and the subsequent allocation of the corresponding funds to equalizing the fiscal capacity of the RF constituent entities. This measure helped reduce interregional differences in budget revenues but at the same time increased the dependence of some regions on federal redistribution and reduced the own revenue sources of individual constituent entities. Thus, the transformation of the mechanisms for distributing revenue sources among levels of the budget system points to the strengthening role of the federal center in regulating interregional financial flows and shaping the fiscal capacity of the RF constituent entities. At the same time, as the data show, changes in the regulatory framework did not lead to a substantial transformation of the interregional structure of fiscal capacity: the composition of regions with the lowest and highest revenues remained stable throughout the period under review. Intergovernmental transfers as a tool for reducing asymmetry in the fiscal capacity of Russian regions To assess the effectiveness of intergovernmental equalization, it is necessary to compare the degree of interregional differentiation of budget revenues before and after the distribution of intergovernmental transfers. To this end, Table 4 presents statistical indicators of tax and non-tax revenues, as well as total revenues of the budgets of the RF constituent entities in per capita terms. Table 4. Changes in selected quantitative indicators of budget revenues per capita across the budgets of the RF constituent entities, thousand rubles Indicator Period under consideration Pre-crisis Pandemic Post-pandemic 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 Tax and non-tax revenues Mean 34.8 33.8 32.8 30.9 31.1 32.4 35.5 36.9 34.7 40.8 41.3 44.7 46.2 Maximum 125.0 118.6 120.4 158.7 110.5 124.8 129.4 139.1 130.8 148.3 146.7 143.9 141.6 Minimum 7.4 7.7 6.9 6.6 6.9 7.3 8.0 7.2 8.2 8.2 8.8 7.8 8.7 Asymmetry range, times 17.0 15.5 17.4 23.9 15.9 17.0 16.1 19.4 16.0 18.0 16.6 18.4 16.4 Coefficient of variation, % 58.8 54.0 62.6 70.1 57.2 57.8 59.6 62.3 57.4 56.5 61.8 55.6 52.9 Decile ratio, times 7.99 7.14 7.91 7.92 6.59 7.20 7.52 7.66 6.40 6.62 7.20 6.78 6.40 Total revenues Mean 49.3 47.2 46.1 41.8 41.5 43.5 48.5 52.0 56.0 60.5 60.5 61.9 61.4 Maximum 137.0 122.3 127.3 162.5 115.3 127.7 133.6 143.0 145.4 154.7 152.8 155.0 150.3 Minimum 29.6 31.8 26.1 26.6 27.7 28.4 31.1 33.7 38.5 39.8 39.4 35.2 33.6 Asymmetry range, times 4.6 3.8 4.9 6.1 4.2 4.5 4.3 4.2 3.8 3.9 3.9 4.4 4.5 Coefficient of variation, % 38.5 33.2 40.4 45.7 37.4 38.9 39.8 39.1 31.1 31.2 36.2 33.9 33.9 Decile ratio, times 2.84 2.58 2.96 2.97 2.68 2.84 2.85 2.79 2.35 2.41 2.65 2.58 2.66 Calculated from: materials from the official website of the Federal Treasury of the Russian Federation. Available at: Table 5. Dynamics of selected statistical indicators of non-repayable receipts, thousand rubles Indicator Period under consideration Pre-crisis Pandemic Post-pandemic 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 Mean 14.5 13.4 13.2 10.8 10.4 11.0 13.0 15.1 21.3 19.7 19.3 17.2 15.2 Maximum 63.6 46.6 59.1 41.7 43.9 53.5 56.9 54.8 62.3 56.4 60.1 63.7 45.8 Minimum 4.0 2.7 2.5 2.1 1.6 1.8 3.8 3.9 7.1 5.0 3.8 2.4 2.5 Asymmetry range, times 16.1 17.6 24.1 19.9 28.3 30.0 15.1 14.0 8.8 11.4 15.8 26.4 18.2 Coefficient of variation, % 64.6 63.3 77.3 68.8 77.6 84.8 78.0 67.9 54.5 55.3 57.1 64.9 64.4 Calculated from: materials from the official website of the Federal Treasury of the Russian Federation. Available at: The data in Table 4 show that interregional differentiation of budget revenues persisted throughout the observation period, but its scale differs considerably for the indicators before and after transfers are allocated. In the pre-crisis period (2012–2019), the coefficient of variation for tax and non-tax revenues ranged from 54.0 to 70.1%, reaching a maximum in 2015 (70.1%). For total revenues, this indicator was markedly lower, in the range of 33.2–45.7%. The asymmetry range for own revenues reached 23.9 times (in 2015), while for total revenues it did not exceed 6.1 times. The decile ratio for own revenues during this period varied from 7.14 to 7.99 times, and for total revenues from 2.58 to 2.97 times. Thus, already in the pre-crisis period, intergovernmental transfers ensured a more than twofold reduction in the gap between the polar groups of regions. In the pandemic period (2020–2021), differentiation indicators reached their lowest values for the entire interval under consideration. The coefficient of variation for total revenues fell to 31.1–31.2%, the asymmetry range to 3.8–3.9 times, and the decile ratio to 2.35–2.41 times. The increase in federal support in 2020–2021 was accompanied by a reduction in regional differences in total revenues (Tab. 5). In subsequent years, differentiation indicators increased somewhat: the coefficient of variation for total revenues was 33.9– 36.2%, and the decile ratio rose to 2.58–2.66 times. This points to the persistence of stable differences in fiscal capacity even after a period of large-scale resource redistribution. Over 2012–2024, per capita tax and non-tax revenues of the regions increased from 34.8 to 46.2 thousand rubles. However, the growth of own revenues was not accompanied by a reduction in interregional differences: the coefficients of variation and asymmetry indicators remained high. Thus, regions’ capacities to form their own revenue bases continued to differ significantly. Unlike own revenues, total regional budget revenues were characterized by a lower degree of heterogeneity. During the period of the largest increase in transfers, primarily in 2020–2021, regional differences narrowed considerably: the asymmetry range for total revenues did not exceed 6.1 times, and the coefficient of variation remained within 31.1–45.7%. This confirms that intergovernmental transfers perform the function of smoothing differences in the fiscal capacity of territories. A comparison of the decile ratios also reveals the difference between the level of the own revenue base and the final fiscal capacity of regions. In 2024, the gap between the top and bottom deciles of regions was 6.4 times for tax and non-tax revenues and 2.66 times for total revenues. Over the entire study period, the decile ratio for own revenues ranged from 6.40 to 7.99 times, whereas for total revenues it ranged from 2.35 to 2.97 times. Consequently, redistribution through the transfer system substantially reduces regional differences but does not fundamentally change regions’ relative positions in the interregional income structure. The dynamics of non-repayable receipts also reflect the changing role of federal support. After a decline in per capita transfers from 14.5 thousand rubles in 2012 to 10.4 thousand rubles in 2016, their volume began to grow and reached a maximum in 2020 – 21.3 thousand rubles per person. The increase in federal financial assistance in 2020 was associated with the implementation of anti-crisis measures during the pandemic. In subsequent years, transfer volumes gradually declined, indicating a return to more standard parameters of intergovernmental fiscal regulation. This suggests that the system of intergovernmental transfers is highly adaptive to external shocks but does not ensure a sustainable reduction in interregional differences in the long term. One of the key objectives of intergovernmental fiscal regulation is to reduce interregional diffe- rences in fiscal capacity while preserving the incentives of the RF constituent entities to develop their own revenue bases (Malkina, 2016; Timushev, Mikhaylova, 2023). To assess the effectiveness of the current system of intergovernmental transfers, we compared the ranks of the RF constituent entities by tax and non-tax revenues and by total regional budget revenues, followed by the calculation of Spearman’s rank correlation coefficient (Fig. 4). For most of the period under review, Spearman’s rank correlation coefficient remained at the level of a strong positive relationship, exceeding 0.7 and reaching 0.83 in some years. The obtained values of Spearman’s coefficient indicate the high stability of the interregional structure of fiscal capacity. In other words, the distribution of the RF constituent entities by total revenues after accounting for intergovernmental transfers largely preserved the order formed on the basis of tax and non-tax revenues. Consequently, the current system of intergovernmental fiscal regulation has a limited impact on changes in the relative positions of regions. Figure 4. Values of Spearman’s rank correlation coefficient Calculated from: materials from the official website of the Federal Treasury of the Russian Federation. Available at: The most noticeable deviation from this pattern was observed in 2020, when the coefficient fell to 0.58 – the lowest level for the entire study period. This points to a change in the nature of intergovernmental redistribution during the pandemic crisis: the volumes of federal support depended less on the initial level of fiscal capacity of the RF constituent entities and were determined to a greater extent by the need to implement anti-crisis measures. Already in 2021, the coefficient rose again to values corresponding to a strong positive relationship (0.70–0.78), indicating a return to the established principles of intergovernmental transfer distribution. Thus, intergovernmental transfers help reduce interregional differentiation in fiscal capacity, but they do not substantially transform the existing hierarchy of the RF constituent entities by income level. Despite the smoothing effect of federal redistribution, regional differences remain quite high. The stability of the interregional hierarchy (Spearman’s coefficient > 0.7 in many years of the study period) means that the system in fact conserves the existing structure of interregional differences without creating conditions for changes in the relative positions of regions. This points to the limited ability of the current system of intergovernmental fiscal regulation to ensure the long-term convergence of regions. Identifying the orientation of federal policy in the provision of intergovernmental financial assistance The nature of intergovernmental redistribution was assessed on the basis of the regression relation- ship between the logarithm of per capita nonrepayable receipts (lnT) and the logarithm of per capita tax and non-tax revenues of the regions (lnR). The estimation results are presented in Table 6. A graphical interpretation of the identified relationship for individual years of the study period is shown in Figure 5: the actual distribution of regions is shown in blue, and the fitted regression line characterizing the orientation of federal transfer policy is shown in red. The values of the coefficient of determination R2 ranged from 0.39 to 0.68, reaching a maximum in 2015. This means that differences in regional own revenues explained between 39 and 68% of the variation in intergovernmental transfer volumes. Consequently, a stable statistical relationship persisted between the fiscal capacity of the RF constituent entities and the scale of federal financial assistance. A fundamentally important result is the consistently negative value of the coefficient β over the entire period under consideration. Its magnitude ranged from -0.61 to -0.98, indicating an inverse relationship between the level of regional own revenues and the volume of transfers provided: less well-off RF constituent entities systematically received larger volumes of federal financial assistance. The statistical significance of the coefficient in all models confirms the reliability of this pattern. An analysis of the dynamics of the coefficient β across the three periods makes it possible to trace the evolution of federal transfer policy. Table 6. Estimation results for the equation ln Ti = a + в • ln Ri + Ei Indicator Period under consideration Pre-crisis Pandemic Post-pandemic 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 R2 0.39 0.49 0.52 0.68 0.62 0.59 0.50 0.55 0.53 0.62 0.56 0.57 0.50 α 4.60 5.09 5.00 5.03 5.37 5.40 5.12 5.32 5.34 5.62 5.53 5.82 5.89 β -0.61 -0.78 -0.78 -0.86 -0.98 -0.97 -0.80 -0.81 -0.70 -0.78 -0.76 -0.86 -0.91 Significance of β + + + + + + + + + + + + + Calculated from: materials from the official website of the Federal Treasury of the Russian Federation. Available at: Figure 5. Relationship between the logarithms of per capita tax and non-tax revenues of regions and the intergovernmental transfers they receive Ln R с2 Ln R Ln R Ln R Ln R Calculated from: materials from the official website of the Federal Treasury of the Russian Federation. Available at: In the pre-crisis period (2012–2019), the coefficient β ranged from -0.61 to -0.98, reaching its highest absolute values in 2016–2017 (-0.98 and -0.97, respectively). This indicates that in those years federal policy was oriented to the greatest extent toward supporting regions with low levels of own revenues. In 2015, the model had its highest explanatory power (R2 = 0.68), pointing to the closest relationship between regional own revenues and transfer volumes. In the pandemic period (2020–2021), the identified relationship noticeably weakened: the coefficient β declined from -0.81 in 2019 to -0.70 in 2020, and R decreased from 0.55 to 0.53. In 2021, the value of в rose to -0.78 and R to 0.62, indicating a partial restoration of the relationship between regional own revenues and transfer volumes, though a full return to pre-crisis parameters had not yet occurred. The decline in the absolute value of β in 2020 reflects the changing nature of federal support during the crisis: the distribution of transfers was determined less by differences in regional tax potential and more by the need to implement anti-crisis measures. This is consistent with the dynamics of Spearman’s coefficient (see Tab. 6), which also reached its minimum in 2020 (0.58), indicating a temporary weakening of the established interregional fiscal hierarchy. In the post-pandemic period (2022–2024), the values of β again approached pre-crisis levels: -0.76 in 2022, -0.86 in 2023, and -0.91 in 2024. This indicates a return to the established principles of intergovernmental transfer distribution, under which the volume of financial assistance is determined to a greater extent by the level of regional own revenues. At the same time, the R2 values in this period (0.50–0.57) remained below the 2015 maximum (0.68), which may point to a certain increase in the complexity of the factors determining federal support volumes, including the growing importance of targeted transfers and program-based instruments. Thus, the regression analysis confirms that federal transfer policy was equalizing in nature throughout the entire study period: funds were directed predominantly to regions with lower levels of own revenues. However, the degree of this equalizing orientation was not constant: it temporarily weakened during the pandemic period, giving way to anti-crisis priorities, and then recovered in subsequent years. At the same time, the identified pattern does not contradict the conclusion about the limited long-term smoothing effect, since even with the preservation of the equalizing orientation of policy, the interregional hierarchy of fiscal capacity remains stable. Conclusion The study has shown that the current system of intergovernmental fiscal regulation in the Russian Federation generally performs an equalizing function but does not eliminate the persistent interregional differentiation of fiscal capacity. The main conclusions can be formulated as follows. 1. Intergovernmental transfers reduce the gap between the most and least well-off regions but do not fully eliminate interregional differences. Throughout the study period, the coefficient of variation for total revenues was 1.5–1.7 times lower than that for own revenues, yet it remained at 31–46%, indicating substantial heterogeneity in fiscal capacity. The decile ratio shows a similar pattern: for total revenues its values remained within 2.35–2.97 times, whereas for own revenues they were 6.40–7.99 times. This points to a significant narrowing of the gap between the most and least well-off regions as a result of intergovernmental redistribution, but it does not allow us to speak of overcoming interregional differentiation. 2. Despite the large-scale redistribution of financial resources through the system of intergovernmental transfers, the interregional hierarchy of fiscal capacity remains stable. Spearman’s rank correlation coefficient exceeded 0.7 for most of the study period, indicating that the relative positions 3. The coronavirus pandemic in 2020 led to a temporary transformation of intergovernmental fiscal regulation mechanisms: the volumes of federal support were determined to a lesser extent by the initial level of regional fiscal capacity. This manifested itself in a decline in Spearman’s coefficient and a weakening of the negative elasticity of transfers with respect to own revenues. However, already in 2021–2022 the parameters of intergovernmental fiscal regulation returned to precrisis values, indicating the adaptability but not the sustainability of the smoothing effect. 4. The results indicate that the current mechanism of intergovernmental fiscal regulation largely fulfills the task of smoothing differences in regional fiscal capacity, but it does not bring about substantial changes in the existing differences in the level of the own revenue base. The stability of the composition of the groups of regions with high and low income levels points to the need to improve mechanisms capable not only of compensating for resource shortages but also of creating conditions for expanding the tax potential of territories. of regions are preserved after they receive transfers. This means that the system of intergovernmental fiscal regulation “adds” resources to existing revenues without fundamentally changing the established structure of interregional differences, thereby effectively conserving the existing asymmetry. One direction for the development of intergovernmental fiscal regulation could be the broader use of incentive elements in the distribution of financial support. When assessing regions’ need for transfers, it is advisable to take into account not only the current level of fiscal capacity but also changes in indicators characterizing the development of their own revenue bases. Another important direction is to differentiate the tasks of various types of transfers. Equalization mechanisms should reduce objective differences in regional fiscal capacity, while incentive-based support instruments could be oriented toward improving the efficiency with which existing economic potential is used. Given the dynamic nature of interregional differences, the parameters of transfer policy require periodic adjustment. This should take into account changes in regional economic structures, demographic processes, and the transformation of the expenditure obligations of the RF constituent entities. The indicators obtained in the study – the coefficient of variation and Spearman’s rank correlation coefficient – can be used as additional tools for analyzing the results of intergovernmental fiscal regulation. They make it possible to assess not only the degree of differences among regions but also changes in their relative positions after the redistribution of budgetary resources. Improving intergovernmental fiscal relations involves not only increasing the precision of fiscal capacity equalization but also finding a balance between the compensatory and incentive functions of transfers. Such an approach could contribute to gradually reducing regions’ dependence on federal support and strengthening their own financial bases. The question of the effectiveness of the current system of intergovernmental equalization can be answered in two ways. On the one hand, the system performs the function of smoothing interregional differences: the coefficients of variation and decile ratios for total revenues are substantially lower than those for own revenues. On the other hand, in the long term the system does not ensure regional convergence or change their relative positions, which makes it possible to describe its effectiveness as limited – effective in the tactical dimension (smoothing shocks) but not in the strategic dimension (sustainably reducing differentiation).